Set your comfort zone
Choose a monthly housing budget that leaves room for living, saving and repairs. Keep an emergency reserve separate.
Your next stepList your savings, recurring obligations and target move date.
 THE BARKER GROUPYOUR FIRST HOME STARTS HERE
KATY · FULSHEAR · WEST HOUSTON
You don’t need to have it all figured out.
You need to know your next step.
From your first budget conversation to the day you get the keys, we help you understand the numbers, the choices, and the fine print.
01 / FROM CURIOUS TO KEYS
The best first purchase starts before the first showing. Build a plan that respects your savings, your timeline, and your everyday life.
Choose a monthly housing budget that leaves room for living, saving and repairs. Keep an emergency reserve separate.
Your next stepList your savings, recurring obligations and target move date.
Ask a lender about pre-approval, available loan options and assistance. Review the full payment and cash needed.
Your next stepGather the income, asset and identification documents your lender requests through a secure channel.
Define your must-haves, test the commute and compare the total cost of each address. Review representation before touring.
Your next stepChoose three priorities and a few flexible preferences.
Review price, deposits, financing, inspections, deadlines and compensation. Compare concessions with a lower price.
Your next stepAsk for a written summary of your offer’s costs and deadlines.
Coordinate inspections, appraisal, title review and final loan approval. Track the contract’s actual deadlines.
Your next stepReview findings and confirm any negotiated repairs or credits in writing.
Review closing figures, verify wiring instructions using a trusted phone number and complete your walkthrough.
Your next stepConfirm funding and possession, arrange utilities, and keep your closing and warranty records.
Before working with an agent, understand who represents you, the services and the fully negotiable compensation. Read TREC’s 2026 written-agreement guidance ↗
02 / START WITH THE FULL PICTURE
Explore a scenario before you tour. These are editable planning assumptions, not current rates, an approval, or a lender quote.
Fixed-rate amortization. Taxes use purchase price × your entered total rate, with no exemptions or future assessment changes. Enter the combined rate including any MUD; 2.8% is an example, not a neighborhood quote. Home insurance excludes separate flood/wind policies unless included in your input. Mortgage insurance is your manual estimate. Closing-cost input should include estimated fees, prepaids and initial escrow; credits apply only to those costs. The estimate omits financed upfront loan fees, separate inspections, option fees, moving, utilities, maintenance, special assessments and any costs not included in your inputs. Assistance and program-specific rules are not calculated. Reserve is additional savings, not a closing charge. Confirm figures with your lender and title company. Understand your Loan Estimate ↗
03 / EXPLORE YOUR OPTIONS
You may have options beyond saving a larger down payment. A participating lender can compare assistance with a loan without assistance so you can see the tradeoffs.
Read our Fulshear assistance guide ↗Start with official TSAHC and TDHCA resources. Eligibility, funding and property rules vary; availability is not a promise of approval.
TSAHC programs ↗ · TDHCA programs ↗Ask if assistance is a grant or a second loan, whether you must repay it when selling or refinancing, and whether it changes your rate, fees or timing.
Compare Loan Estimates for the same scenario: monthly payment, upfront costs, credits and long-term borrowing costs.
CFPB loan comparison guide ↗A QUICK PERSONAL CHECK-IN
You don’t need every box checked to reach out. This checklist helps you see what to work on next.
0 of 5 planning steps checked.
For your planning only. This checklist is not a credit or mortgage assessment. Your answers stay on this page and reset when it reloads.
Let’s work on your next step ↗04 / FIND YOUR FIT
Compare your commute at the times you travel, insurance quotes, the actual tax district, HOA documents and the condition of each home.
Start with area context. Verify the county, tax district and school assignment for the exact address.
Explore Katy ↗02Compare established and newer communities, total carrying costs and your daily routes.
Explore Fulshear ↗03Use the local first-purchase guide to organize the questions you bring to your agent and lender.
Explore the buyer guide ↗Contact Niky before your first model-home visit to confirm that builder’s agent-registration policy. Compare lender incentives, contract terms, tax assessments, inspections and completion dates.
Price cut or rate buydown? Read the comparison ↗05 / GO A LITTLE DEEPER
Local guidance from the Barker Group. Older market figures and program examples in these articles should be reconfirmed before you act.
Understand the expenses beyond your down payment.
↗02 / THE OPTIONSUse the local overview to prepare questions for a participating lender.
↗03 / THE PROCESSWalk through a local purchase from preparation to closing.
↗04 / THE TRADEOFFSSee why the biggest advertised incentive may not fit your plan.
↗06 / NO QUESTION TOO SMALL
Not always. Down payment requirements depend on the loan and your eligibility. A smaller down payment may add mortgage insurance or other costs. Ask a lender to compare your total monthly payment and cash needed, not only the down payment.
Possibly. TSAHC and TDHCA offer homebuyer programs through participating lenders. Income, credit, property, education and other rules apply. Ask whether assistance is a grant or a second loan, when repayment is triggered, and how it changes your rate and fees.
No. Cash to close also reflects closing costs, prepaid items, escrow funding, credits and deposits already paid. Your lender’s Loan Estimate and final Closing Disclosure provide the transaction-specific figures.
Discuss the services, agreement length, exclusivity and negotiable compensation in your written agreement. Texas requires an appropriate written agreement before an agent working with a prospective residential buyer shows property, with specific exceptions such as some listing-brokerage open houses. Ask who the agent represents.
Compare the full cost and condition of each address. New homes may offer incentives but can have completion uncertainty, builder-specific contracts and changing tax assessments. Resale homes may offer an established setting but need repairs. Review inspections, insurance, taxes, HOA documents and your timeline for either choice.
Track every contractual deadline with your agent. Coordinate inspections, lender requests, appraisal and title review; resolve agreed issues; confirm insurance and closing funds; and complete a final walkthrough. Your lender and title company confirm funding and possession arrangements.
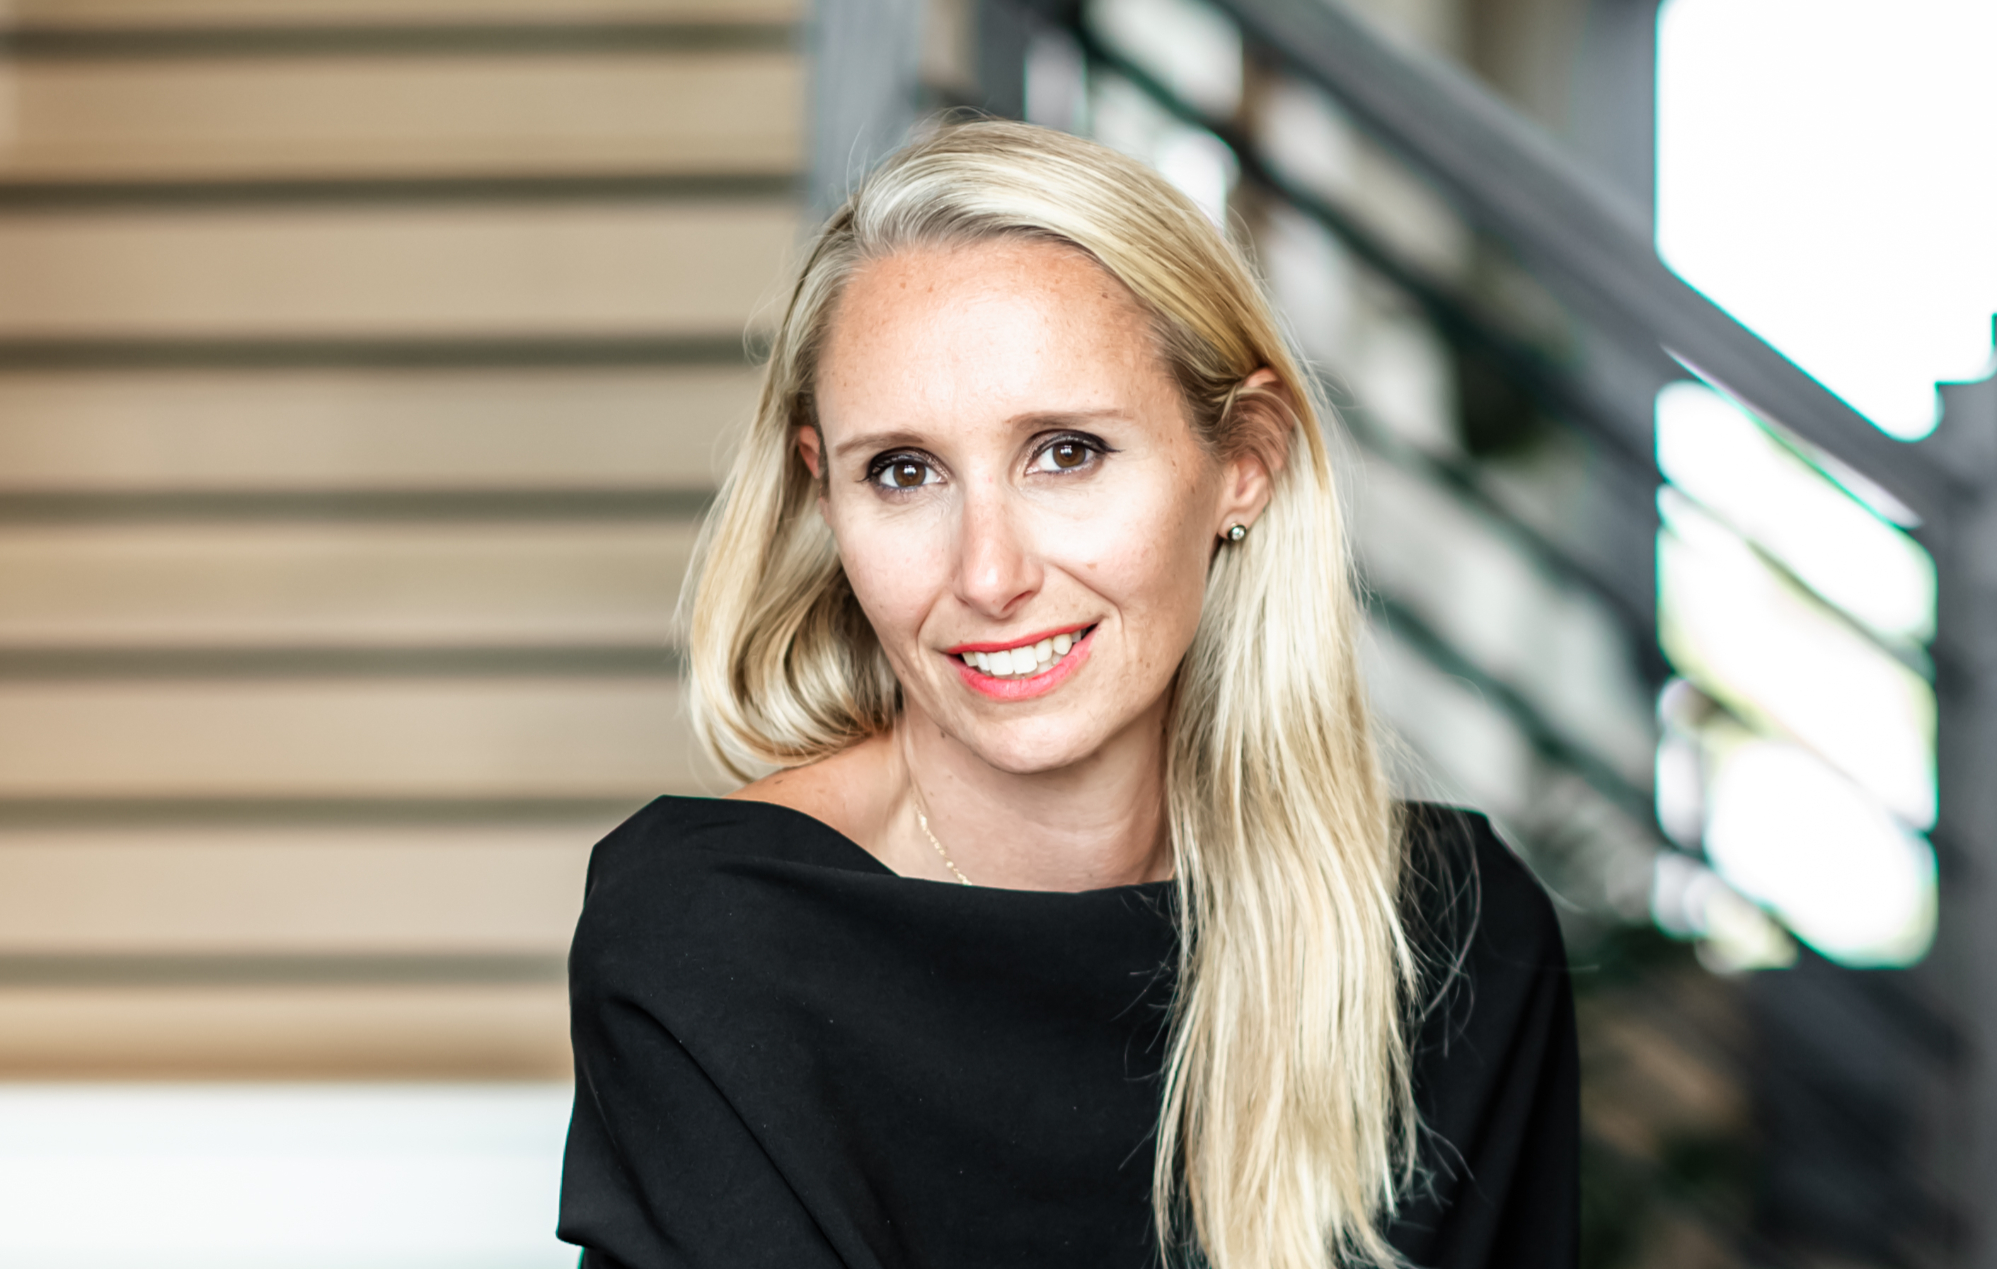
LOCAL GUIDANCE. A HUMAN ON YOUR SIDE.
I’m Niky Barker, Team Leader and REALTOR® with The Barker Group at Keller Williams Signature. I help first-time buyers across Katy, Fulshear, Cypress, Richmond, Rosenberg and West Houston turn questions into a practical plan.
Tell me where you’re looking, when you’d like to move, and what feels unclear. We’ll start there.
Niky Barker · REALTOR® · MRP
920 S Fry Rd, Katy, TX 77450
917-399-7099 · niky@barkergrp.com
Email opens a draft in your email app. Nothing is submitted through this page. Please don’t send financial documents by email; ask your lender for a secure upload method.